Table of Contents
Why Mortgage Note Holders Sell What to Expect Choosing a Buyer The DC Note Market Types of DC Notes Premium Pricing What DC Note Sellers Say Common QuestionsWhy Mortgage Note Holders Sell Their Washington DC Mortgage Notes
Amerinote Xchange has been purchasing privately held mortgage notes nationwide since 2006. Notes secured by District of Columbia real estate are consistently among the strongest we review due to the fact that property values in Washington DC are among the highest in the country. The more equity in the collateral (the property), the more money the note will fetch when it is taken to market.
Mortgage Note holders sell for all kinds of reasons. Some are settling an estate and need to divide the asset among heirs. Some are retiring or relocating and no longer want to manage the collection of payments. Others simply have a better use for the money today than collecting it over the next fifteen or twenty years. Whatever the reason, the process is the same, and it costs you nothing to find out what your mortgage note is worth.
A Washington, D.C. mortgage note is priced on its own merits, and there is more nuance in that pricing than most sellers expect. That being said, a performing note secured by an occupied residential or commercial property will typically land between 70 and 90 cents on the dollar of the unpaid principal balance at the time of sale, depending on the characteristics and the circumstances surrounding the asset. In a nutshell, whatever the borrower still owes you on the day you sell your mortgage note is the number the offer works from, and the payment history, the equity, the rate, and the paperwork decide where in the range it lands. We have been purchasing mortgage notes secured by Washington, D.C. real estate since 2006, and once we review your information, a firm written offer typically follows within 2 to 5 business days, depending on how complex the property and the transaction turn out to be.
Most of the mortgage note holders we work with did not set out to be in the finance business. They sold a property and agreed to carry the financing for the buyer, or they inherited a mortgage note through an estate, or they lent money to someone they know and secured it against real estate. If that describes your situation, you are what the industry calls a private mortgage note holder, and the monthly payments you collect can be converted into a lump sum of cash.
- Stop waiting on monthly payments, get your full payout now
- Recycle your capital into new investments and opportunities
- Fund a lifestyle change, retirement, relocation, or a fresh start
- Cash out to provide for your family or settle an estate
- Eliminate the burden of servicing, collections, and compliance
- Remove borrower default risk from your portfolio
Sell Your Washington DC Mortgage Note
In Five Simple Steps
Our streamlined process makes it easy to convert your D.C. mortgage note into cash.
Most sellers close within 30 days or less.
Submit Your Note Details
Fill out our quick form with your note details. Takes less than 2 minutes.
Receive Your Quote
We analyze your note and come back with a competitive, no-obligation cash offer, typically within days.
Accept the Offer
Review the offer, ask questions, and accept when you’re ready. No pressure, no deadlines.
Due Diligence
We handle the title work, appraisal, and document review at our expense.
Get Paid
Funds arrive by wire or by check at closing, according to your preference. Fast, secure, done.
What to Expect When You Sell a Mortgage Note in Washington, D.C.
If you have never sold a mortgage note before, it helps to understand what the experience will look like before you pick up the phone, due to the fact that most of the mortgage note holders we work with in Washington, D.C. are going through this process for the first and only time. Two documents do most of the heavy lifting when it comes to receiving a quote:
- The sale information. The sale price, the down payment, and the date of sale. All three live on the closing statement (the HUD-1) from the day the property sold, so most sellers only need to dig up a single page.
- The promissory note itself. This is the document that carries the terms of the deal: the interest rate, the payback schedule, what happens on default, the legal venue, and the rest of the language a buyer reads before pricing a mortgage note.
Between them, those two documents contain the information most mortgage notes are quoted on, which means you are closer to a number than you might think. If part of your file has wandered off over the years, contact us anyway and speak with a live person, as rebuilding a thin file is something we help note holders do all the time.
Once you accept the offer, the remainder of the work belongs to us. We will order the title work, arrange a drive-by appraisal of the property securing the mortgage note, and verify the balance and payment history, all at our expense, which includes a brief call with your borrower (known in the industry as a payor interview) in order to confirm that the payment records match the reality on the ground. The entire process of selling a mortgage note in DC will generally run anywhere from 15 to 30 days, depending mostly on the schedules of the local appraisers and the title company, and at closing the funds arrive by wire or by check, whichever you prefer.
How to Choose the Right Mortgage Note Buyer
When it comes to selling a mortgage note on the secondary market, your odds of reaching your financial goals and walking away with the highest possible payout improve considerably when the buyer on the other side of the table is a direct mortgage note buyer with a track record you can verify. We would rather you take the time to vet us (and everyone else) than accept the first number that lands in your inbox, so here is the checklist we would hand a family member who was preparing to sell a mortgage note:
- Work with a direct mortgage note buyer when possible. A direct buyer purchases with its own capital and does not charge commissions, whereas most note brokering firms most certainly do, and that commission comes straight out of your payout.
- Look for staying power. Only choose a company that has been buying mortgage notes for more than five years, as longevity in this industry is earned one closed transaction at a time. Amerinote Xchange has been purchasing mortgage notes since 2006.
- Check the rating. Leading mortgage note buyers are accredited by the Better Business Bureau with an A rating (at the very least) and no unresolved complaints, and a strong rating with a clean record tells you the company stands behind its transactions.
- Search the company’s name. Type the mortgage note buyer’s name into a search engine and see what comes up, due to the fact that a company with a history of scams or bad behavior will usually be exposed in the results long before you would discover it on your own.
- Trust your gut. Does the buyer seem trustworthy, has it answered every one of your questions completely, and does it appear to be looking out for your best interest rather than its own bottom line? If the answer is yes across the board, chances are you have found a dependable mortgage note buyer, and if you do not feel comfortable, simply move on to another.
A mortgage note is often the largest asset a person will ever sell aside from the property itself, and ten minutes of homework on your buyer is a small price to pay for getting the sale right. If you want the long version, we wrote a full guide on how to choose a mortgage note buyer.
The Washington DC Mortgage Note Market
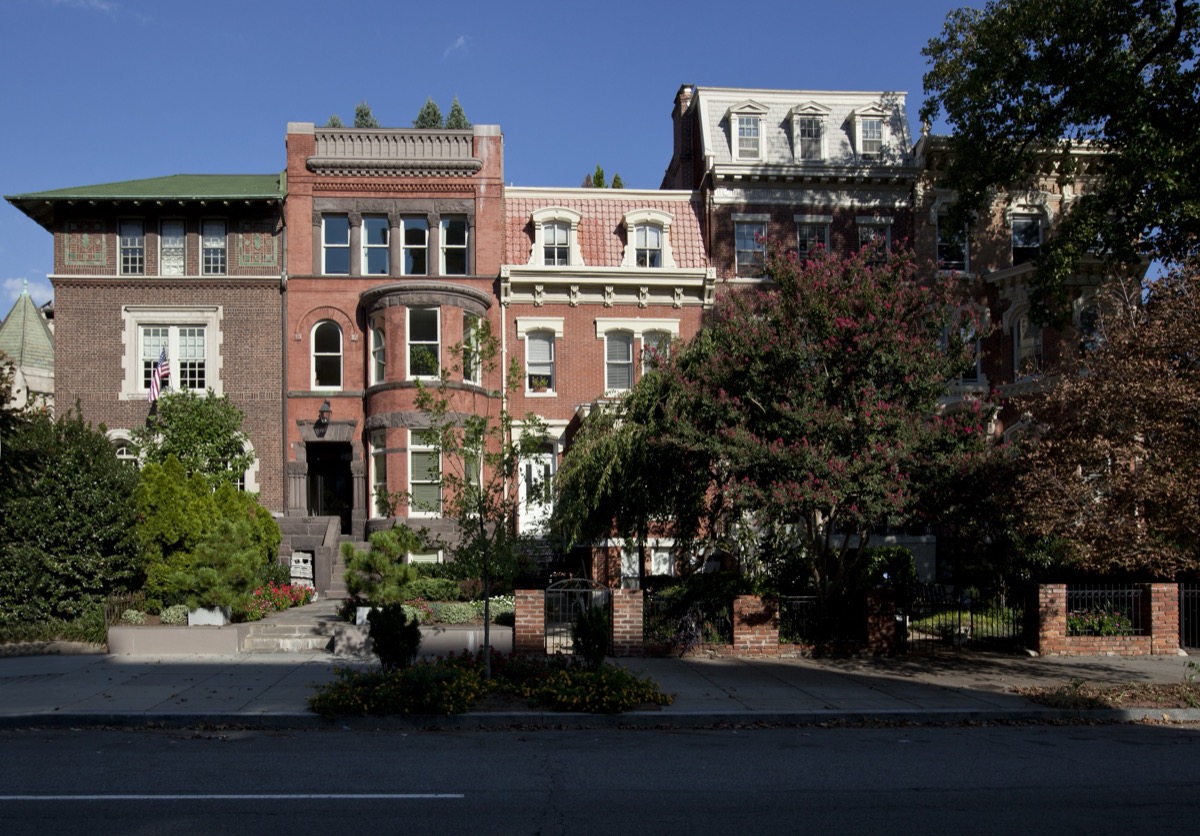
D.C. is one of the highest-value real estate markets in the country. The District’s median sale price sits near $695,000 per Redfin mid 2026 reporting (well above the national figure) and its housing stock is structurally scarce: the federal Height Act caps vertical development, so well-located rowhouses, condos, and small multi-family buildings hold their value through market cycles. Demand is anchored by the federal government, law and consulting firms, universities, hospitals, and the international diplomatic community. For mortgage note holders, that combination of expensive, supply-constrained collateral and a deep professional buyer pool translates into strong pricing on the secondary market. D.C. secures most private real estate loans with deeds of trust, and lenders may pursue either a non-judicial (power-of-sale) or judicial foreclosure path. The District’s foreclosure mediation program adds a step to the non-judicial process, which is one reason experienced note buyers price D.C. assets carefully, and why working with a buyer who knows the DC process matters.
Washington DC Neighborhoods We Serve
- Capitol Hill & Eastern Market: historic rowhouses, generational ownership, steady private-sale financing
- Georgetown & West End: luxury historic district, high-value collateral
- Upper Northwest: Chevy Chase, Cleveland Park, Tenleytown, premier residential corridor
- Shaw, Logan Circle & U Street: condo and mixed-use boom
- Navy Yard & Capitol Riverfront: DC’s fastest-growing new-construction submarket
- NoMa & H Street Corridor: transit-driven development, condo and mixed-use notes
- Petworth & Brightwood: rowhouse renovation pipeline, active investor financing
- Anacostia & Southeast: seller financing fills the gap where bank lending thins out
These are just the best-known neighborhoods, we buy notes in every quadrant of DC. NW, NE, SE, SW, it doesn’t matter. Residential, commercial, mixed-use, multi-family, land, condos, rowhouses, if a note is secured by D.C. real estate, Amerinote Xchange would love to review it for purchase.
Considerations for Non-Performing Mortgage Notes
A non-performing mortgage note, one where the payments are showing up late or have quit showing up altogether, gets priced through a different lens. When Amerinote Xchange runs a non-performing note through diligence, the review is built around the following:
- The payment record. When the last payment arrived, and which month on the schedule that payment actually covered.
- The foreclosure clock in the jurisdiction. The longer the process runs where the property sits, the deeper the discount on the mortgage note. Our foreclosure laws guide covers the state-by-state details.
- The property tax status. Delinquent taxes stand in front of the mortgage note in the payoff line, and that seniority affects the offer.
- The default rate written into the note. A default interest provision changes what the instrument earns once performance stops, and buyers price said provision accordingly.
- The value of the property today. The collateral is what ultimately secures the debt, and the current value matters far more than the value from the original appraisal.
In order to check the maximum rate a note can legally carry, our usury laws by state reference lays out the limits.
What Is Your Washington DC Note Worth?
Get an estimated offer on your mortgage note in under 60 seconds. No personal info required.
Mortgage Note Calculator
Get an estimated offer on your mortgage note in under 60 seconds.
This is an estimate only. Your actual offer may be higher or lower based on additional factors including credit, property condition, and documentation. No obligation.
Get Your Official QuoteTypes of DC Notes We Purchase
We buy virtually every type of seller-financed note secured by D.C. real estate.
Residential Deed of Trust Notes
Rowhouses, condos, and single-family homes from Capitol Hill to Chevy Chase and every D.C. neighborhood.
Commercial Notes
Office buildings, retail, and mixed-use properties across downtown, K Street, and DC’s commercial corridors.
Land & Development Notes
Infill lots, development parcels, and land assemblages, scarce, valuable ground in a height-capped city.
Deed of Trust Notes
D.C. uses Deeds of Trust as the primary security instrument. We handle all District-specific requirements and documentation.
Multi-Family Notes
Rowhouse conversions, duplexes, and small apartment buildings. D.C.’s deep rental market supports solid note valuations.
Business Notes
Seller-financed businesses, restaurant sales, franchise transfers, and business real estate transactions throughout the DC area.
Why Washington DC Mortgage Notes Usually Fetch Premium Pricing
-
Deed of trust jurisdiction
D.C. secures most private real estate loans with deeds of trust, keeping recovery paths clear for note buyers. -
Among the highest home values in the nation
A $695,000 median sale price means large equity cushions standing behind D.C. mortgage notes. -
Structurally scarce housing supply
The federal Height Act caps vertical development, well-located D.C. property holds value through market cycles. -
Deep professional employment base
Government, law, consulting, universities, and the diplomatic community anchor housing demand year-round. -
Dense rowhouse & condo stock
An active renovation and investor pipeline generates a steady flow of seller-financed transactions across the DC Metro.
Washington DC Mortgage Note Market at a Glance
Powering smarter mortgage note sale decisions across the District of Columbia.
Where Washington DC Mortgage Notes Are Most Active
Neighborhood pricing: Zillow / Redfin, mid-2026 • Submarket intelligence: Amerinote Xchange
Why Washington DC Mortgage Notes Usually Fetch Premium Pricing
-
Deed of trust jurisdiction
Washington, D.C. secures most private real estate loans with deeds of trust, keeping recovery paths clear for note buyers. -
Among the highest home values in the nation
A $695,000 median sale price means large equity cushions standing behind D.C. mortgage notes. -
Structurally scarce housing supply
The federal Height Act caps vertical development, well-located D.C. property holds value through market cycles. -
Deep professional employment base
Government, law, consulting, universities, and the diplomatic community anchor housing demand year-round. -
Dense rowhouse & condo stock
An active renovation and investor pipeline generates a steady flow of seller-financed transactions across the DC Metro.
Get Your Free Washington DC Note Quote
Fill out the form below and receive a no-obligation cash offer, typically within a few days.
Common Questions About Selling a Mortgage Note in Washington, D.C.
What DC Note Sellers Say
Ready to Sell Your Washington DC Mortgage Note?
No-obligation quote. We cover all costs associated with the purchase.
Get Your Free Quote